At its recent conference, Labour announced Great British Grid (GBG), “a new publicly owned body within Great British Energy that will help accelerate the delivery of the electricity network infrastructure Britain needs”.
The slow pace at which GB is replacing its aging electricity grid, and extending it to bring renewable energy to customers, is well known to users who want to electrify but find themselves in a years-long queue. What is GBG and will it speed up grid expansions?
Even within the energy industry the question of the role of GBG was described recently by one longstanding industry member as “a big question that’s not answered”.
It is clear that GBG is not going to take over the electricity network and turn it into a publicly owned monopoly. Just the opposite. In fact, GBG fits more comfortably within a longstanding plan to increase competition in the electricity network sector.
More competition
Networks are often described as a ‘natural monopoly’ in their geographical area. They have to be a ‘common carrier’ for users, similar to the open access to the roads network. This is the case once the network is built and connected. However the government wants to see more competition in the building and connections phase, and in ‘adopting’ new network once it is in place, believing this will eventually be faster and cheaper than leaving it to the existing networks.
There is already competition of this type in the distribution networks (with low voltage cabling, equivalent to B and local roads). In contrast, with very few exceptions, extensions and connections to the high voltage electricity ‘motorways’ remain in the hands of three transmission owners (TOs). Regulator Ofgem and the government want that to change.
One exception to monopoly ownership is the cables that connect offshore assets – mainly wind farms – to the onshore transmission network. Ofgem introduced a 25-year so-called ‘Offshore Transmission Owner’ (OFTO) licence for these assets, granted by auction. The long licence, relatively simple asset and risk management profile, and predictable revenue stream made them attractive assets and Ofgem was able to claim that OFTO ownership was cheaper than if the assets had been part of the existing TO network. New legislation extends the OFTO model to some of the new network needed onshore, with a 25-year concession to operate granted to the winner of an auction.
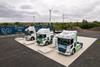
Meanwhile, the government is consulting on another competition option it describes as ‘self build and transfer’. This option would allow companies building, for example, HGV charging parks, to build the electrical connection themselves. This would give the investing company flexibility over planning applications, local consultation and timing of the build. This could reduce costs and – by consulting with the public on the new asset and its connection together – could speed up planning approval.
It is within these aspects of the grid build-out that GBG seems likely to play its part.
The benefit of GBG
Announcing GBG, the government said, “Great British Grid will bring together public and private investment to support the delivery of critical network infrastructure across the country. Working alongside existing network operators, it will help accelerate projects, increase competition and support the delivery of the grid upgrades needed to power Britain’s future.”
That suggests GBG would be in competition with the existing TOs, OFTO operators and other companies entering the new TO build market.
What can it bring that is different? An earlier government-owned body, the Green Investment Bank, was seen to be useful in bringing new companies into consortia to invest in new renewable energy projects and similarly GBG is expected to bring together consortia to invest. While GIB could not take responsibility for due diligence for its consortium partners, its presence gave some comfort and perhaps help to smaller investors. Widening the pool of investors results in more competition and, hopefully, lower prices.
Can GBG assure the supply of the electrical equipment to be installed? The UK is just one among many countries expanding their electricity grid and the supply of transformers, insulators, cable and other components is very restricted. Ofgem has already relaxed some of the rules that previously stopped network companies from ordering equipment for future years [in the past, Ofgem argued that if the equipment was not needed consumers would have paid for ‘stranded assets’ and companies should not take that risk]. Will GBG help its partners, and the UK industry as a whole, be regarded as ‘good customers’ who can strike reliable – and priority - deals with equipment suppliers?
Whether these benefits will be realised and grid expansion sped up remains to be seen. But Ofgem may also hope that GBG will offer a benefit in giving the regulator sharper tools in regulating the monopoly TOs.
TOs send financial reports to Ofgem, but the regulator can never know exactly how they deliver their projects and whether they are the best possible value for money. The new competitive processes, and GBG’s presence within them, may give Ofgem more information about cost and timing, and give it sharper regulatory tools to hold all the companies to account.
Its possible that these options could mean GBG can kick GB’s network expansion into a higher gear. It remains to be seen whether the possibility becomes a certainly.